Lawrence, Evans & Co., LLC has been recognized among the Top 10 sell-side advisors on Axial’s 2026 Top 50 Lower Middle Market Healthcare Investors & M&A Advisors list.
The annual list highlights Axial’s most active healthcare members over the prior 12 months. Rankings are based on deals brought to market, buyer interest in those processes, healthcare-focused investment mandates, and transactions that advanced through the deal funnel.
Lawrence, Evans & Co. is a national boutique healthcare financial advisory firm based in Columbus. We advise small and middle-market companies on mergers and acquisitions, capital raising, and special situations, with a focus on healthcare providers and services, logistics, and business services. Our work is concentrated with companies typically up to $250 million in revenue and/or $15 million in EBITDA.
We appreciate the recognition from Axial and the companies and capital partners who continue to work with us.
We advise small and middle-market companies on mergers and acquisitions, capital raising, and special situations, with a focus on healthcare providers and services, logistics, and business services. Our work is concentrated with companies typically up to $250M in revenue and/or $15M in EBITDA.
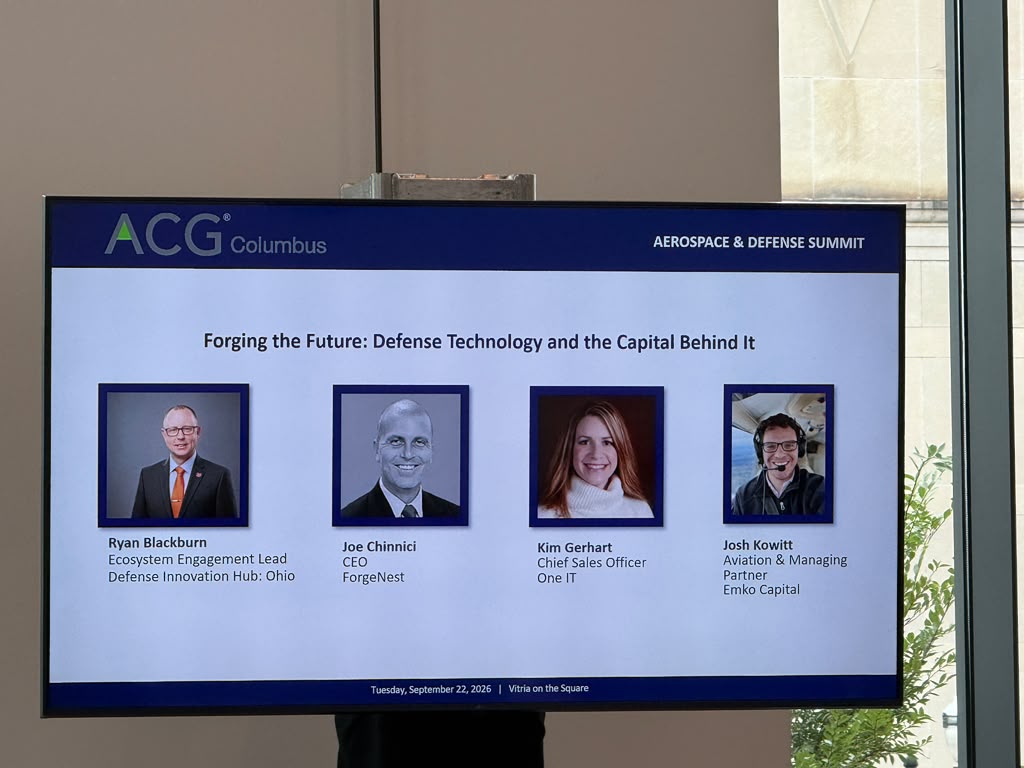
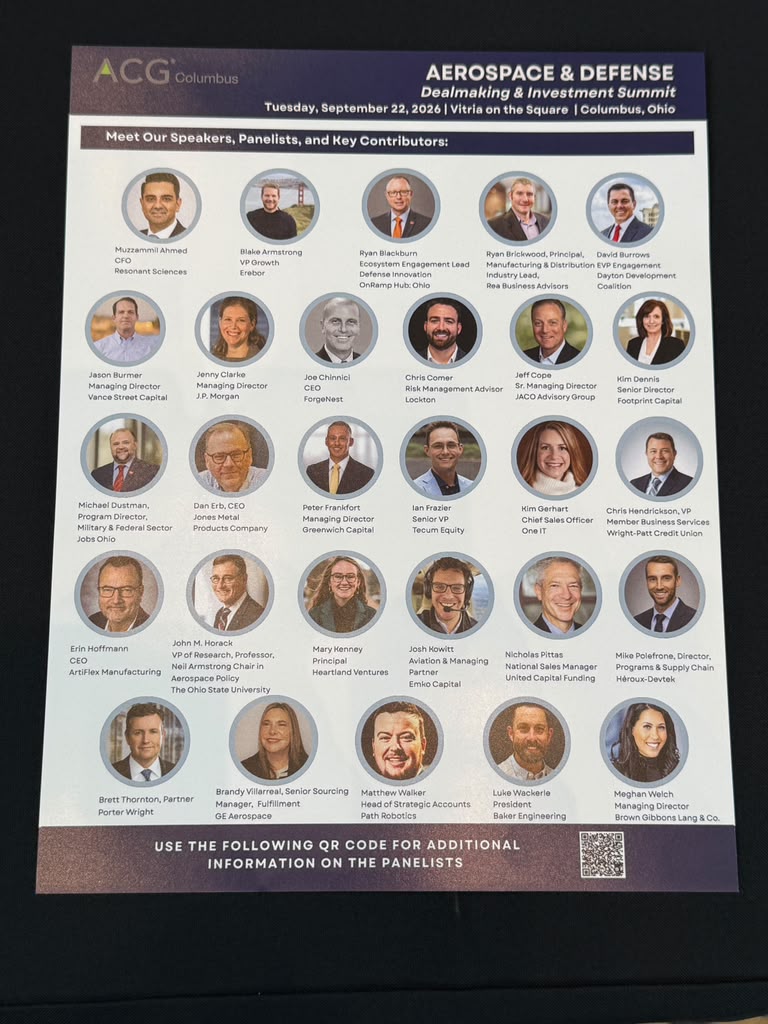
Aerospace & defense and healthcare have meaningful overlap — dual-use technology, medical logistics, cybersecurity, space health, and the capital that supports companies operating in both ecosystems.
In 2020 we published our bioastronautics paper about the potential overlap in industries. Read the paper here: https://lnkd.in/guiYk2jk
We are currently working on a medical drone industry paper. If you have insight or input, we would value your feedback. Read the working draft here: https://lnkd.in/gU8dgSYU
Managing Partner Neil Johnson will be on-site throughout the event. If you are attending, please connect with Neil in person, or visit us at https://lnkd.in/daXdAZvF.
Our other team members Spenser L., Kurtavya Joshi and Byron A. will also be present if Neil is not available.
CareTrust REIT (NYSE: CTRE) Acquires Southwest Skilled-Nursing Portfolio for $400 Million First public print of a transaction effective September 1. The book is 2,622 licensed SNF beds, triple-net to the incumbent operator with inflation escalators and renewal options. Structured as a joint venture; CareTrust put in about $380 million from cash and settled equity forwards and models an 8.6% stabilized yield. Sourced off-market in markets where both landlord and operator already have scale. Year-to-date deployment is now about $1.9 billion and Q3-to-date about $710 million. Management reloaded the near-term pipeline at about $600 million. (Link)
Lisata Therapeutics (NASD: LSTA) Acquires Marea Therapeutics; $225 Million PIPE Concurrent Stock-for-stock reverse merger plus PIPE. RA Capital, Forbion, Third Rock, Alpha Wave, Perceptive, Sofinnova, Omega, Surveyor/Citadel, Columbia Threadneedle, Nantahala, Affinity, venBio and Rock Springs filled the round. Combined cap table: legacy Lisata about 2.4%, Marea holders about 59.5%, PIPE about 38.1%. Assets are MAR001/005, an ANGPTL4 monoclonal in Phase 2b for severe hypertriglyceridemia, and MAR002, a growth-hormone-receptor antagonist headed to Phase 2 in acromegaly. Runway into 2028; key reads targeted for the fourth quarter of 2027. (Link)
Veracyte (NASD: VCYT) acquires Convergent Genomics for $150 million in cash plus up to $30 million in milestone payments, adding urine-based bladder cancer testing. Veracyte closed its purchase of Convergent Genomics on September 14. It paid $150 million in cash at closing, subject to customary adjustments, with up to $30 million more tied to UroAmp publication and reimbursement milestones. Convergent was founded in 2015 in partnership with Oregon Health & Science University and runs a CLIA-certified lab in South San Francisco. Its UroAmp urinary tumor DNA assay is validated for monitoring therapy response and post-treatment surveillance in non-muscle-invasive bladder cancer. The asset sits alongside Decipher Bladder and TrueMRD, so Veracyte now covers urine, tissue and blood across the bladder cancer pathway. Management expects no material impact on 2026 EBITDA guidance. (Link)
Oaktree commits up to $115 million in milestone-based capital to Saol Therapeutics ahead of the FDA decision date for SL1009. Funds managed by Oaktree will provide up to $115 million to Saol Therapeutics, a private clinical-stage drug company in Roswell, Georgia. An initial tranche funds launch preparation, and the rest is released as regulatory, clinical and commercial milestones are met. The lead drug, SL1009 (sodium dichloroacetate), treats pyruvate dehydrogenase complex deficiency, a rare mitochondrial disease with no approved therapy. The FDA rejected an earlier application in 2025. Saol resubmitted, and the FDA’s decision date is December 30, 2026. Later tranches would fund SL1009 in congenital lactic acidosis and expand SL1002 into more pain indications and spasticity. (Link)
Agora makes a $47 million first investment in Vheda Health, a Columbia, Maryland outcomes and analytics platform for health plans. Agora is a San Francisco private equity firm focused on healthcare technology, founded by Neil Vangala. It has invested $47 million in Vheda Health. This is Agora’s first deal and the first institutional capital in Vheda’s 13-year history. The previously bootstrapped company runs chronic-condition and maternity programs for high-risk Medicaid, Medicare and Special Needs Plan members. It cites more than $975 million in savings for health plan partners and an average 3:1 return on investment. Co-founder and CEO Shameet Luhar stays. The money funds expansion beyond 18 states, new analytics products and targeted acquisitions. (Link)
Ambu (Nasdaq Copenhagen: AMBU B) acquires U.S.-based TIMS Medical (Foresight Imaging) for $45 million upfront plus up to $20 million in milestones to advance its EndoIntelligence platform. Ambu, the Danish single-use endoscopy leader, has bought Foresight Imaging, LLC, which trades as TIMS Medical. It is paying $45 million upfront and up to $20 million in milestones, for total consideration of as much as $65 million. Founded in 2004, TIMS builds hardware and software that record procedure imaging and integrate it into hospital EMR and imaging systems. Its flagship TIMS MVP is widely used in ENT procedures, including FEES exams. The business has about 55 employees, roughly $15 million in annual revenue and around 7,000 installations across U.S. hospitals. Ambu expects the deal to accelerate revenue growth and kept its FY2025/26 outlook unchanged. (Link)
WJRJJ Ventures, owned by Copart (NASD: CPRT) founder Willis Johnson, completes a $40 million private placement in HealthStream (NASD: HSTM). WJRJJ Ventures bought 1.5 million HealthStream shares at $29.50 each. That comprised 1,355,932 new shares for about $40 million and 144,068 existing shares bought from CEO Robert Frist Jr. for about $4.25 million. Frist remains the largest shareholder, with about 16.4%. Johnson, a Nashville-area entrepreneur, was also the first investor in Empath Nursing, founded in 2025. HealthStream sells workforce technology to hospitals and will use the money for product investment and possible acquisitions. (Link)
Arsenal Capital Partners–backed Endpoint Clinical acquires Boston-based Bluefin, a clinical supply forecasting and planning technology provider. Endpoint Clinical, the randomization and trial supply management vendor Arsenal acquired in 2024, has bought Bluefin, a Boston cloud platform for planning clinical supply demand and distribution. The add-on moves Endpoint upstream from RTSM execution into forecasting. Supply plans will link to live enrollment and inventory data, so sponsors can anticipate shifts rather than react to them. Bluefin will keep operating independently and will still connect to competitors’ RTSM systems. Endpoint will add implementation, quality, project management and customer support. Bluefin CEO Andy Maltun stays. (Link)
Seven Hills Capital–backed Spa Medicca of Canton, Ohio acquires Dr. Nicholas E. Sherock LLC & Associates, an Ohio women’s health practice in Massillon and Orrville. Spa Medicca has acquired Dr. Sherock & Associates, a two-location women’s health group in Massillon and Orrville. Dr. Nicholas Sherock leads a five-person clinical team offering gynecologic care, hormone replacement therapy, minimally invasive surgery and aesthetic services. Those services map onto Spa Medicca’s focus on medical aesthetics, hormone optimization and women’s health. The deal adds density in northeast Ohio after earlier work such as Amy Brenner, MD & Associates in Cincinnati. Patients keep existing providers and locations. (Link)
Gauge Capital–backed Reliable Medical acquires Freedom in Mobility and Action Seating & Mobility, expanding CRT coverage across Alabama, Tennessee, Oklahoma, Arkansas and Colorado. Reliable Medical is a Nashville CRT and home medical equipment provider Gauge recapitalized from Seven Hills in January. Freedom in Mobility adds three sites in north Alabama and Tennessee; president Teresa Glass Owens and COO Forrest Owens join. Action Seating & Mobility adds Tulsa, Oklahoma City, Muskogee, Fayetteville, Sherwood and Denver — manual and power chairs, custom seating, ATP-led fitting and repair. Combined network is more than 50 locations. Two add-ons in one week on the same platform. (Link)
NMS Capital launches Asurgence Medical by recapitalizing ENDOCORP and acquiring Medical Optics from Probo Medical. NMS partnered with management to recapitalize Endoscopy Corporation of America of Southfield, Michigan and at the same time bought Medical Optics of Tamarac, Florida from Probo Medical. ENDOCORP supplies more than 15,000 repair-part SKUs for flexible endoscopes. Medical Optics repairs and resells flexible and rigid scopes across manufacturers. Both keep their names as Asurgence subsidiaries. Former Probo CEO Michael Asmer becomes CEO. Thesis is aging equipment fleets and hospital pressure to avoid OEM overhaul pricing. (Link)
Amulet Capital Partners closes a continuation vehicle to recapitalize US Fertility. New and existing investors participated. US Fertility was formed in 2020 and now supports more than 120 clinic and IVF lab locations and over 200 physicians. It has treated more than 400,000 patients. The deal builds on L Catterton’s 2025 entry as co-lead alongside Amulet and the physician partners. Amulet, a healthcare-only sponsor managing about $3.8 billion, stays involved. The new capital funds geographic expansion and clinical innovation. (Link)
Sheridan Capital Partners acquires a majority stake in PtEverywhere, a Raleigh-based practice management and payments platform for physical therapy clinics. Sheridan completed a majority investment in PtEverywhere. The Raleigh platform brings scheduling, clinical documentation, billing and collections into one workflow for small and mid-sized outpatient physical therapy clinics, including cash-pay and hybrid reimbursement models. CEO Andrew Shofner stays. Sheridan plans organic growth and add-ons that broaden the product into adjacent rehab segments. The deal sits next to Sheridan’s 2025 investment in post-acute billing vendor National Care Systems. (Link)
Martis Capital– and Din Ventures–backed Archway Dental Partners acquires Veale Dental, its first Massachusetts practice. Archway Dental Partners, based in Danbury, Connecticut, acquired Veale Dental, a two-location general practice in South Easton and Dartmouth. This is Archway’s first Massachusetts practice and its third acquisition of 2026, after five deals in 2025. The group began as the four-location Dental Associates of Connecticut and now supports more than 40 practices across Connecticut and New York. Entry into a new state rather than an add-on in an existing market. (Link)
Neuberger and KKR (NYSE: KKR) agree to acquire a significant minority stake in Datavant, which remains controlled by New Mountain Capital. Funds managed by Neuberger Capital Solutions and Neuberger Private Markets, together with KKR’s Strategic Investments Group, agreed to buy a significant minority stake in Datavant. New Mountain Capital, an investor since 2014, keeps control. Datavant’s network spans more than 80,000 providers and 75 of the top 100 health systems, and its data touches about 90% of the U.S. population. Growth capital into a scaled asset rather than an exit, funding further digitization and clinical AI. Closing expected in the fourth quarter of 2026. (Link)
Parthenon Capital–backed MRO acquires Vyne Medical from TJC-owned Vyne, adding clinical data intake and document processing. MRO, a Norristown clinical data management platform, acquired Vyne Medical from Vyne, a TJC portfolio company. Vyne Medical turns paper, fax, voice and image inputs into structured data for more than 800 hospitals. Together the companies serve over 2,500 hospitals and 35,000 clinics. Intake tools feed MRO’s medical-records release and data exchange services. Vyne Dental is not part of the deal and stays with TJC. Clean sponsor-to-sponsor handoff. (Link)
NewSpring-, Kineticos-, HealthQuest- and Great Point–backed Kincell Bio Merges with Cellipont to Form Kincellis Advanced Therapies U.S. cell-therapy CDMO combination. Kincell’s immune-cell shop plus Cellipont’s stem, iPSC, MSC, dendritic, exosome and mRNA work. About 140,000 square feet across Gainesville, Research Triangle Park and The Woodlands; 16 qualified GMP suites; more than 150 GMP batches released; 10 INDs this year; 200-plus staff. Darren Head is CEO. Equity led by NewSpring with Kineticos Life Sciences, HealthQuest Capital and Great Point Partners; debt from J.P. Morgan. (Link)
Arlington-Backed Everest Clinical Research Acquires Firma Clinical’s Data Services Unit Toronto data-first CRO buying Firma DS, a biometrics and clinical-data book that has touched more than 1,000 studies and 60-plus NDAs across oncology, neurology, rare disease, hepatology and nephrology. Adds delivery capacity in the U.S. and Asia-Pacific. Firma DS clients get Everest’s full-service stack — regulatory, operations, safety, medical writing — on one CRO. Arlington Capital has owned Everest since 2020. (Link)
Gauge-Backed Rovia Clinical Research Acquires Pinnacle Research Group and Cullman Clinical Trials in Alabama Site-network add-ons on Gauge’s Rovia platform. Pinnacle is an Anniston-area multi-specialty site founded in 1998, with 500-plus completed trials and Phase I capability. Cullman Clinical Trials is its north-central Alabama partner site. The pair gives Rovia owned density in a state it did not previously control. Gauge has funded the site roll-up since the 2024 platform launch. Separate from Reliable Medical, another Gauge healthcare vehicle. (Link)
HealthEdge- and United Western–Backed Veridian Healthcare Acquires ScarScience from Mitchell-Vance Medical-grade silicone scar sheets and gels into plastic surgery, dermatology and physical-therapy channels. Brand add-on onto a wound-and-scar distribution platform rather than a clinic buy. Robert Friedberg remains CEO; Jessica Rowen stays on the seller side of the handoff. HealthEdge Investment Partners and United Western Group are the sponsors. (Link)
Medallion acquires Andros, an NCQA-certified credentials verification organization, creating a credentialing platform covering more than one million providers. Medallion, a San Francisco AI-assisted credentialing and payer-enrollment platform, acquired Andros, an NCQA-certified CVO serving health plans, health systems, provider groups and telehealth companies since 2013. The combination brings more than one million providers across nearly 400 organizations and health plans onto one platform. Andros verifies data on more than 8 million providers and runs about 300,000 credentialing checks a year. Health-plan customers will move onto Medallion’s automated verification tools and AI outreach agents. (Link)
Abry Partners–backed Centauri Health Solutions of Tempe, Arizona acquires Iowa-based Benny the Benefits Navigator to expand its SSI/SSDI eligibility technology. Centauri acquired Benny the Benefits Navigator, an Iowa startup founded in 2024 by Jeremy Shapiro, James Vancel and Joel Segre. Its AI platform replaces paper forms with a conversational digital intake for SSI and SSDI applications. Benny folds into Centauri’s Member Connect disability eligibility service, which already reaches more than 60 million lives. Latest add-on under Abry after the 2025 MedAllies purchase. (Link)
Ignitus Recovery acquires AIM Health Boulder, a Colorado mental health and substance-use treatment program for young adults. Englewood-based Ignitus acquired AIM Health Boulder, a 20-year Boulder program treating adults 18–30 through PHP and IOP at the historic Earl House. Ignitus plans to keep existing programs and add residential treatment, alumni engagement and long-term recovery support. Founder Danny Conroy said he chose Ignitus to carry the program forward. CEO Steve Millette committed to no disruption for clients, staff or referral partners. (Link)
Stony Brook Medicine Community Medical Group acquires South Shore Digestive Medicine, a Bay Shore, New York gastroenterology practice led by Dr. Darius Sorbi. The community physician arm of Stony Brook Medicine acquired South Shore Digestive Medicine in Bay Shore. Dr. Darius Sorbi trained in internal medicine at Stony Brook and completed his GI fellowship at Mayo Clinic. He specializes in advanced endoscopy, biliary and pancreatic disease and GI cancers. The practice is now listed at 10 Brentwood Road, Bay Shore, alongside Stony Brook GI sites in Commack and Lake Grove. Extends the SUNY-owned academic system’s coverage onto Long Island’s South Shore. (Link)
AKTIV Against Cancer Merges with CancerFit Exercise-oncology combination. AKTIV is the U.S. sister of Norway’s Aktiv mot kreft — hospital gyms branded Pusterom in Norway and AKTIVcenter in the U.S., research funding at Memorial Sloan Kettering, first U.S. site at Summit Health in New Jersey. CancerFit is the digital and program counterpart. No price and no cap table on the open wire. Merger of two mission-aligned exercise-as-treatment platforms, not a clinic roll-up. (Link)
Daia Orthodontics & TMJ Orthopedics acquires four former docbraces clinics in New Brunswick and Prince Edward Island, its first expansion outside the U.S. Rochester Hills, Michigan-based Daia acquired four clinics that previously operated under the docbraces name, in Grand Falls and Woodstock, New Brunswick, and Charlottetown and Summerside, Prince Edward Island. The founder-owned practice goes from one location to five. Founder Dr. Hadi Daia is certified in both the U.S. and Canada and has treated patients at these clinics since 2021, converting an existing clinical relationship into ownership. Current clinical and administrative teams stay. No outside sponsor was named. (Link)
Medartis Holding (SIX: MED) Acquires M.A.R.C. Institute in Doral, Florida First permanent training site outside Europe and the group’s largest, with 36 surgical stations and capacity for 140 participants. Name and general manager Heloise Peixoto stay; the IBRA partnership continues; universities, societies and other device companies keep access. Satellite activity in São Paulo, Rio and Curitiba. Osteosynthesis implant maker buying education infrastructure, not a clinic roll-up. (Link)
Xenetic Biosciences (NASD: XBIO) to Acquire Santersus AG in an All-Stock Exchange; Combined Company to Be Santersus Bio Agreement dated September 14, public print September 16. Swiss NucleoCapture blood-purification device plus Xenetic’s DNase platform against neutrophil extracellular traps. Santersus holders about 85%, Xenetic about 15% on a fully diluted basis. Pipeline includes Breakthrough Device-designated work in sepsis and SLE. Combined company expected to trade as Santersus Bio. Close targeted in the fourth quarter on a stockholder vote and Nasdaq listing of new shares. (Link)
Venture Deals and Other
Vitruvian Partners leads Angle Health’s $600 million financing at a $2.7 billion valuation, with Town Hall Ventures, Blumberg Capital, Portage Ventures, Prudential Financial (NYSE: PRU)’s PruVen Capital and Y Combinator participating. London-based Vitruvian Partners led a $600 million equity financing in Angle Health at a headline $2.7 billion valuation. It combines a $200 million Series C with a $400 million tender offer for existing shareholders. New investor Town Hall Ventures joined existing backers Blumberg Capital, Portage Ventures, PruVen Capital and Y Combinator. The San Francisco company provides AI-driven health benefits to more than 5,000 small and mid-sized employers, with nearly $1 billion in annualized premiums. It reports 120% growth and four profitable quarters in a row. (Link)
Thoreau leads a $100 million funding commitment to Penelope Health, with Bertelsmann Healthcare Investments, Twine Ventures and Seedcamp participating. Thoreau, the healthcare investment platform led by former New Mountain Capital president Matt Holt, has committed $100 million to London-based Penelope Health. Existing backers Bertelsmann Healthcare Investments, Twine Ventures and Seedcamp joined. The funding comes with a partnership to build shared infrastructure for real-time payments and clinical coverage rules. Penelope’s platform tracks insurer coverage policies for more than 200 million Americans across over 15,000 procedure and drug codes. The amount is a commitment rather than a closed round. (Link)
JMI Equity leads Archy’s $50 million Series C, with TCV, Entrée Capital, Bessemer Venture Partners, CRV and Alven participating. JMI Equity led a $50 million Series C in Archy, a San Jose AI platform for running dental practices. Existing investors TCV, Entrée Capital, Bessemer, CRV and Alven joined. Total funding now stands at $97 million. Built-in AI agents handle claims and collections, visit notes, insurance eligibility, patient communications and analytics. Archy serves more than 1,000 practices in 45 states and processes over $300 million in payments a year. (Link)
Catalio Capital Management leads AVAVA’s $45 million financing, made up of $30 million in equity and a $15 million debt facility. Catalio, AVAVA’s first institutional investor, led a $45 million package of $30 million in equity and a $15 million debt facility. The relationship includes $10 million of growth capital from Catalio’s Structured Opportunities Fund in 2024. Boston-based AVAVA sells aesthetic laser devices built on Focal Point Technology, which delivers energy to targeted depths in the skin. The money funds commercial expansion, new products and international growth. (Link)
Obvious Ventures leads Mithrl’s $20 million Series A, with Headline and AGI House participating. Obvious Ventures led a $20 million Series A in Mithrl, a California company building AI infrastructure for drug developers. Headline, AGI House and several pharma executives participated. Its second-generation platform, Mithrl-1, pairs a proprietary biomedical model with agents that choose models and manage cost. It runs inside each client’s environment. The company says top-10 pharma companies and clinical-stage biotechs already use it, with a goal of 50% faster IND timelines. (Link)
Neon leads Ayble Health’s $16 million Series A, with Unum Group (NYSE: UNM)’s Unum Ventures, Upfront Ventures, M13, Ohio-based Cleveland Clinic Ventures, DigiTx and Accomplice participating. Neon led an oversubscribed $16 million Series A in Boston-based Ayble Health. Total capital raised now exceeds $27 million. Ayble runs an AI-enabled virtual clinic for digestive conditions, sold to national health plans, large employers and benefit platforms. It reports a 47% average improvement in symptoms and at least a 3:1 return for customers. The money strengthens AI care tools and expands the company into autoimmune conditions. (Link)
GOA Therapeutics Emerges from Stealth with $15.5 Million; Unveils GOA26 for Acute Alcohol Intoxication Dallas preclinical shop. In an IND-enabling porcine model after 1.2 g/kg oral ethanol, blood alcohol concentration was 61.3% lower versus control at 20 minutes. No FDA-approved drug rapidly lowers BAC today. IND targeted by year-end 2026; first-in-human work in 2027. Data were presented the same day at AAST in Dallas. (Link)
Khosla Ventures leads Nara Health’s $14 million pre-seed and seed financing, with Long Journey Ventures and Superior Studios participating. Khosla led $14 million across pre-seed and seed in Nara Health, formerly Avant Health. Long Journey Ventures, Superior Studios and angels joined. The Chicago company administers health plans for self-insured employers using AI — benefits, claims, care coordination and member support. Nara has more than 25,000 members and has processed over $600 million in claims. CEO Sid Sinha said the money funds Chicago hiring and platform scale. (Link)
Flare Capital Partners leads Kairon Health’s $5 million round, with Tau Ventures, Lightbank, General Advance and Pave Health Ventures participating. Flare led a $5 million round in Kairon Health, joined by Tau Ventures and existing backers Lightbank, General Advance and Pave Health Ventures. Founder Nick Bartz spent nine years at Aledade. The New York AI platform turns claims, records, admission alerts, lab and pharmacy data into task lists for staff at ACOs, health systems and physician groups. It covers more than one million patients across 30-plus states under Medicare, Medicaid and commercial value-based contracts. (Link)
Addus HomeCare (NASD: ADUS) to Acquire Advent International–Backed AccentCare’s Personal Care Division for Approximately $275 Million Advent International’s AccentCare is selling only the non-New York personal-care book; hospice and skilled home health stay with the seller. Addus, a scaled non-franchise home-care operator listed on Nasdaq, is paying about $275 million after customary adjustments and funding the check with revolver and cash. The assets serve roughly 13,700 patients a day across 10 states and should add about $280 million of annualized personal-care revenue, a 19% lift to Addus’s base. Density is heaviest in Texas, Illinois, California and Arizona, with additional volume in Colorado, Georgia, Minnesota, Pennsylvania, Tennessee and Washington. The purchase extends Addus’s Medicaid-heavy personal-care footprint rather than buying hospice or Medicare home health. (Link)
Axogen (NASD: AXGN) to Acquire BioCircuit Technologies for $200 Million in Cash Axogen is paying $200 million cash for BioCircuit, with $1 million held back for the post-close true-up, and is funding the check with a concurrent $208.7 million common-stock offering. The prize is NerveTape, the first FDA-cleared sutureless device for peripheral nerve repair, plus ConformaWrap. BioCircuit did about $11 million of revenue in 2025 and is running at roughly $24 million on more than 14,000 implants across 400-plus hospital and ASC accounts. Convertible notes convert and an unrelated electronics R&D unit is spun out before closing. Management expects year-one accretion to growth, adjusted EBITDA margin and adjusted EPS while remaining free-cash-flow positive. (Link)
COSCIENS Biopharma (TSX: CSCI) Acquires Nualtis from AtaiBeckley (NASD: ATAI) for $15 Million Plus Earnouts COSCIENS is buying Montreal oral-thin-film CDMO Nualtis, formerly IntelGenx, from AtaiBeckley for $15 million plus four earnouts equal to 10% of adjusted EBITDA in 2027–2030. Nine million dollars was paid at close; $6 million is deferred six months. The plant is FDA- and Health Canada-inspected and runs VersaFilm for human therapeutics and VetaFilm for veterinary use, with an existing pipeline and pharma partnerships. A concurrent first tranche of unsecured convertibles raised about $6 million toward a $20 million cap and funded the closing check. For a small TSX-listed ingredients company, the deal is a way to own a purpose-built film platform rather than build one. (Link)
Patient Square–Backed Hanger to Acquire AEA’s Numotion; Combined Company to Be Called Hanger Numotion Patient Square is putting two mobility platforms under one roof in a cash purchase. Hanger contributes 925 U.S. orthotic and prosthetic clinics; AEA Investors’ Numotion contributes more than 200 complex-rehab and mobility sites in the United States and Canada. Combined they will serve more than 1.5 million patients a year and keep both brands and clinical operations. Numotion CEO Mike Swinford, in the seat since 2014 after two decades at GE including GE Healthcare Services, will run the combined company as Hanger Numotion; Pete Stoy steps aside. The combination is PE-backed specialty-provider consolidation across complementary mobility verticals, not a single-clinic tuck-in. (Link)
Apple (NASD: AAPL) Acquires Berkeley Brain-Sensing Startup Sonera Apple has bought Sonera, a Berkeley company that builds chip-scale magnetic sensors to read neural and muscle activity without implants or skin-contact electrodes. Co-founders Nishita Deka and Dominic Labanowski started the firm in 2018 out of UC Berkeley; it later raised about $20 million, including an $11 million 2023 seed, and marketed an S1 biomagnetic chip for muscle sensing, prosthetics and wearables. Magnetic readout is meant to avoid the skull-dampening that limits electrical EEG. Apple has not said what the team will work on. Outside write-ups point at Watch-class neuromuscular monitoring and hands-free accessibility; those uses are inferred, not confirmed. (Link)
Labcorp (NYSE: LH) Acquires Great Point Partners’ MLM Medical Labs Great Point Partners is exiting MLM Medical Labs, the central- and specialty-lab it built in the United States, Germany and South Africa. Labcorp is folding the network in so it owns laboratories on four continents — North America, Europe, Asia and Africa — including the first CAP-accredited central lab on the African continent. MLM adds biomarker and specialty capacity for multinational trial work that Labcorp previously covered through a mix of owned sites and partners. The industrial logic is one operator, one scientific and regulatory stack, on global protocols rather than a patchwork of affiliate labs. (Link)
General Catalyst– and CVS Health Ventures–Backed H1 Acquires Defacto Health to Add Provider-Network Intelligence H1, the physician-data platform backed by General Catalyst and more recently CVS Health Ventures, is buying Defacto Health, a specialist in payer-network and directory intelligence. Defacto maps which clinicians sit in which networks and which plans they accept — the data health plans use to test directory accuracy, isolate error clusters and benchmark access. It was already a data partner. Co-founders Ron Urwongse and Tarun J. Theogaraj, both formerly of CAQH, join H1 and will keep running the product inside the Doctor Graph rather than as a standalone brand. The buy sits against ongoing CMS and plan pressure on directory accuracy as provider and network data change continuously. (Link)
Eir Partners Acquires Accumulus Technologies, the Life-Sciences Regulatory Cloud Platform Eir Partners is buying Accumulus Technologies, a San Francisco regulatory-cloud platform that connects more than 75 agencies to life-sciences sponsors. The product is built for multi-agency review rather than point-to-point filings and already has live Veeva RIM connectivity. Accumulus was spun out of nonprofit Accumulus Synergy in 2025 so it could raise capital and sell commercially; CEO Francisco Nogueira stays. Eir, a healthcare software firm, is treating the asset as a category platform at the intersection of life sciences, technology and global regulation rather than a point tool for a single agency workflow. (Link)
1315 Capital Buys Argonaut’s Life Sciences and Diagnostics Unit; Business Relaunches as Aluris Sciences 1315 Capital is buying only Argonaut’s life-sciences and diagnostics manufacturing unit and relaunching it as Aluris Sciences. Telegraph Hill Partners, New Vale Capital and management keep the Carlsbad aseptic fill-finish CDMO. Aluris runs formulation through commercial production for diagnostics, life-sciences and combination-product customers and will operate independently; staff and resources were already largely separate, so live programs do not move. Sale proceeds recycle into Argonaut’s fill-finish capacity. The structure is a clean carve-out rather than a whole-company sale of a dual-vertical CDMO. (Link)
SK Capital–Backed Precera Medical Acquires Additive Metal Services Precera Medical, the four-plant orthopedic and interventional OEM SK Capital carved out of LISI Medical in November 2025, is adding Additive Metal Services of Port Huron. The shop brings metal-injection molding and sinter-based additive manufacturing for precision components — robotic-surgery end effectors and distal interventional-catheter parts among the named uses. Precera already runs design, prototyping, precision machining, micro-feature work, automation and finished-device assembly across Minnesota and France. Customer programs and tooling stay. The add-on is process-capability adjacency on a new platform, not a new end-market. (Link)
Avesi Partners–Backed Danforth Health Acquires Ambit RD Avesi Partners’ Danforth Health is buying Ambit RD, a rare- and specialty-disease shop that sells commercial strategy, advanced analytics and AI-assisted patient identification into biopharma. CEO Rob Sederman and CCO Ned Kitfield stay. Ambit is the latest add onto a platform that has already rolled up Asymmetry Group, PharmaDirections, VPMR, Advyzom, Benchworks, Elite BioPharma Consulting and Argot Partners. The thesis is a single commercialization backbone from clinic through launch rather than another standalone consultancy sitting beside the last one. Rare-disease commercial work is one of the few remaining fee pools that still pays for specialist analytics. (Link)
RiverGlade Capital Makes Platform Investment in Senior Living Residences RiverGlade Capital is backing Senior Living Residences, the Braintree operator of 24 independent living, assisted living and memory-support communities across New England and the broader Northeast. Founder Robert Larkin and CEO Tadd Clelland stay; the SLR name stays. The company has run service-enriched buildings for nearly four decades and includes the Compass Memory Support Neighborhoods line. RiverGlade is a healthcare PE firm that typically partners with founder-led lower-middle-market operators and funds people, operations and both organic and acquired growth. No price was printed. The check is meant to keep expanding the Northeast book without changing the operating identity. The transaction closed in July; this is the first public write-up. (Link)
Latticework Capital–Backed Beacon Behavioral Partners Acquires Albaron’s Prime Psychiatry Latticework Capital’s Beacon Behavioral Partners is buying Prime Psychiatry from Albaron Partners, which backed founder Dr. Efosa Airuehia in 2022. Prime is outpatient and interventional psychiatry — medication management plus TMS and Spravato — for children, adolescents and adults across Dallas–Fort Worth and Austin. The clinics join a national behavioral platform that has been adding partner practices across the Southeast and Midwest while leaving local brands intact. Local physicians stay. The sale is a sponsor-to-sponsor handoff of a regional interventional-psychiatry density play rather than a de novo clinic build. (Link)
Santé Ventures–Backed Jaguar LAA Acquires Johnson & Johnson (NYSE: JNJ) Laminar Program Assets Santé Ventures formed Jaguar LAA with members of the Laminar team to take Johnson & Johnson’s left-atrial-appendage program out of a strategic and finish development as an independent company. The asset is a catheter-based LAA-closure approach aimed at stroke-risk reduction in non-valvular atrial fibrillation and designed to leave minimal hardware in the left atrium. Key program assets and the originating engineers move together. The structure is a classic medtech carve-out plus NewCo financing rather than a license back to the seller. (Link)
InTandem-Backed Ivy Fertility Acquires Santa Barbara Fertility Center InTandem Capital’s Ivy Fertility is adding Santa Barbara Fertility Center, opened in 2008 by reproductive endocrinologist Rene Allen after a USC fellowship. Allen stays and continues to practice. The same announcement adds five other physicians across Ivy’s network and a build-out in male fertility. Local brand is retained. Ivy is already a multi-state IVF platform; Santa Barbara is a coastal California density add with an existing physician and lab book, not a 100%-owner partnership that leaves control unchanged. (Link)
LongueVue-Backed Summit / Pinnacle Acquires Dallas Research Institute LongueVue Capital’s Summit / Pinnacle site network is buying Dallas Research Institute, a single-site DFW unit opened in 2024 with the late hepatologist Dr. Stephen Harrison and focused on MASLD, MASH and obesity trials. Principal investigator Dr. Pedro Castillo Jr. stays. The buyer already runs 15 owned U.S. sites plus 110-plus partner sites in eight countries, with IRO, recruitment, medical-communications and early-phase CRO affiliates under the same roof. The add is metabolic-site density in a high-enrolling metro rather than a new therapeutic vertical. (Link)
VSS-Backed Olympus Cosmetic Group Acquires Gallaher Plastic Surgery & Med Spa VSS-backed Olympus Cosmetic Group is buying Gallaher Plastic Surgery & Med Spa, its first Tennessee practice and the entry into Knoxville. Dr. Tom Gallaher stays under a physician-led model and the local brand is being kept. Olympus is a surgeon-founded aesthetics platform assembling plastics and med-spa density market by market rather than a roll-up that rebrands every site on day one. The add-on is a local-brand-preserved clinic purchase into an unpenetrated MSA, not a new platform launch. (Link)
Frazier-Backed LUX Infusion Acquires Two Northeast Ambulatory Infusion Centers Frazier Healthcare’s LUX Infusion is buying two Northeast ambulatory infusion centers: South Jersey Pediatric and Adult Infusion Center in Cherry Hill, N.J., and Northeast Infusion Therapy in Latham, N.Y. The purchases are separate from the August Infuse IQ deal. LUX is a clinician-led home-plus-center platform after the BioMatrix rebrand. The two sites bring chair capacity and existing physician-referral books in two new Northeast MSAs, which is the density the platform needs if home infusion and AIC are going to sit on the same operating system. (Link)
Altas Partners and L Catterton Agree to Acquire Fullscript from HGGC Altas Partners and L Catterton are buying a majority stake in Fullscript from HGGC and Snapdragon Capital Partners. The Ottawa platform, founded in 2011, sells practitioners an integrated stack of diagnostics, treatment planning and dispensed supplements and already cites more than 135,000 clinicians, about 10 million patients a year and $1 billion-plus of revenue. HGGC and Snapdragon put $240 million in during 2021, later added Rupa Health for labs, and used a Leonard Green continuation vehicle in 2025. The new sponsors are taking majority control to fund further clinical-tool and North American expansion. (Link)
Revvity (NYSE: RVTY) to Acquire France’s Human Cell Design Revvity is buying Human Cell Design, a French specialist in human pancreatic beta-cell models. The flagship line is EndoC-βH5, sold with specialized media, reagents, preclinical services and the NatLine cell-line platform for diabetes, obesity and other metabolic work, including GLP-1 and GPCR programs. Revvity is treating the company as a reagents tuck-in that sits next to HTRF, AlphaLISA, ATPlite and high-content screening rather than a new instruments franchise. Human-relevant cell models have become a procurement item for metabolic and incretin discovery groups that want to reduce animal-only screening. (Link)
Novo Holdings Makes Minority Investment in China’s ForYou Medical; GL Capital Remains Majority Novo Holdings is taking a minority stake in ForYou Medical; GL Capital remains majority owner. The Huizhou company is a CDMO focused on advanced wound-care manufacturing for global device customers rather than a branded finished-goods play. Novo Holdings’ China head framed the check as the firm’s first China medtech ticket and part of a larger Asia ramp in both check size and local team. The industrial logic is specialized converting capacity plus China-to-global customer access, not a control deal or a domestic hospital chain. (Link)
Nvidia- and Health System–Backed Artisight Acquires TMG Global Artisight, the Nvidia- and health-system-backed smart-hospital vendor, is buying TMG Global, a healthcare infrastructure and site-readiness shop that runs large technology deployments. The team comes in-house so health systems have one accountable path from clinical-space and MDF/IDF surveys through hardware staging, install, validation, training and Day-1 support. Artisight’s platform uses computer vision and ambient sensing to run operating rooms and inpatient units; the bottleneck has been deployment, not the model. The purchase is operational capacity for enterprise rollouts, not a new clinical product. (Link)
Sanofi (NASD: SNY) and Braun Family–Owned Cheplapharm to Form Mature-Medicines Partnership Sanofi is moving a tail of 20 mature medicines and three plants to Cheplapharm, the German family-owned established-products company controlled by the Braun family, and taking a 26.4% equity stake in return. The plants are Csanyikvölgy in Hungary (about 400 employees), Jurong in Singapore (about 100) and Ploërmel in France (about 65), and they include manufacturing for Lovenox/Clexane. The two sides have collaborated since 2014. Commercial transfer is planned to start in early 2027, then the sites, subject to works-council consultation and regulatory approvals. Structure is a partnership and minority stake, not a signed control sale of Cheplapharm. (Link)
Venture Deals and Other
Forus Raises $150 Million Series C at a $3 Billion Valuation, Led by Bain Capital Ventures Bain Capital Ventures led a $150 million Series C in Forus at a $3 billion valuation, four months after a $160 million Series B. Every existing institution re-upped, including Thrive, General Catalyst, Accel, Redpoint, BoxGroup and Pear; cumulative capital now exceeds $300 million. Forus, formerly Tandem, builds an AI agent per prescription that sits between the physician, payer, pharmacy and manufacturer to clear access work and is free to doctors and patients. Coverage is all 50 states and about 85% of U.S. residential ZIP codes. Proceeds go to specialty expansion, more agents and commercial headcount. (Link)
BrainChild Bio Closes $116 Million Series A BrainChild Bio raised $116 million in a Series A led by a family fund and foundation aligned with the pediatric-oncology mission; Seattle Children’s, the original investor, and WRF Capital joined. Proceeds fund ILLUMINATE, the Phase 2 pivotal trial of BCB-276, a B7-H3 CAR-T, in diffuse intrinsic pontine glioma, and push triple-target construct BCB-214 toward first-in-human glioblastoma work. The platform is licensed from Seattle Children’s. Steven Brugger is CEO. DIPG remains a category with almost no approved options, which is why a mission-aligned family check can lead a round of this size. (Link)
TwoStep Therapeutics Raises Oversubscribed $62.5 Million Series A; FDA Clears TS-104 IND Insight Partners and Medical Excellence Capital led an oversubscribed $62.5 million Series A in TwoStep Therapeutics; Pfizer Ventures and Merck KGaA’s M Ventures co-led, with NFX, 2048 Ventures and Stanford joining. Cumulative capital is $71.2 million. The company’s peptide-drug conjugate binds five tumor-associated integrins rather than a single antigen, a design aimed at tumors that lack a clean one-target profile. FDA has cleared the TS-104 IND; Phase 1 enrollment is expected later this year. Proceeds also fund a radioligand program and next-generation peptide conjugates. (Link)
Kura Oncology (NASD: KURA) Launches Caspian Therapeutics with $50 Million Series A Led by BVF; Eli Lilly (NYSE: LLY) Participates Kura Oncology launched Caspian Therapeutics with a $50 million Series A led by BVF Partners. Kura contributed menin-inhibitor IP including KO-7246, invested $4.3 million and keeps about 49%. Eli Lilly and the T1D Fund joined, alongside Invus, Montanova and Kura management. Proceeds take KO-7246 into Type 1 and Type 2 diabetes proof-of-concept and fund a second menin asset for broader cardiometabolic use; oncology stays at the parent. Kura CEO Troy Wilson is executive chair; Rob Spencer is president and COO. Phase 1 is targeted by the end of 2027. (Link)
Implicity Raises $40 Million Growth Round Led by IRIS and Five Arrows IRIS and Rothschild & Co’s Five Arrows led a $40 million growth round in Implicity. The Cambridge and Paris company already covers more than 250 medical centers and monitors 120,000-plus patients a day across the United States, France and Germany. The platform is FDA-cleared AI sitting on connected pacemakers, defibrillators and implantable loop recorders; published real-world data cite a 26% mortality reduction and a 4% drop in hospitalizations versus conventional remote monitoring. Proceeds go to U.S. commercial hiring, U.S.-specific product work and further AI, including heart-failure prediction. (Link)
Epsilon Health Emerges from Stealth with $27.6 Million Led by AlleyCorp AlleyCorp led a $27.6 million stealth round in Epsilon Health; Uncork Capital, Renegade Partners, SemperVirens and Jack Altman joined. Epsilon is an AI-native radiology practice — physicians plus models — not a point-solution vendor selling into someone else’s group. It already serves more than 250,000 patients, reads 2,500-plus studies a day, and handles more than half the volume at one large outpatient imaging chain. Management says it is on track for about 1% of daily U.S. X-rays this year. Head of machine learning is ex-DeepMind; the CMO is former Envision Radiology CMO. (Link)
GenHealth.ai Raises $16.5 Million Series A Led by Flare Capital Partners Flare Capital Partners led a $16.5 million Series A in GenHealth.ai. Craft Ventures and Obvious Ventures re-upped; Eniac, InHealth Ventures, Epsilon Health Investors and ARTIS came in. Cumulative capital is about $30 million after a 2023 seed. The Boston company, spun out of 1upHealth, deploys agents inside existing EHRs and payer systems for intake, eligibility, prior authorization, billing, denials and appeals rather than selling another system of record. Management cites a 34% revenue lift and up to 80% admin-cost reduction; Guidehealth reports 4x productivity on intake and prior auth. (Link)
UrgentIQ Raises $15 Million Series A Led by Five Elms Capital Five Elms Capital, a vertical-software growth shop with more than $3 billion under management, led a $15 million Series A in UrgentIQ. The product is an AI-native EMR and operating system built for urgent care rather than a hospital or primary-care fork. Proceeds fund a native billing module, AI documentation and coding, live insurance verification and an AI checkout agent, plus commercial headcount. Founder Nat Gibbs is building against a market that still runs on hospital-grade EMRs never designed for high-throughput episodic visits. Earlier seed capital was not a named institutional growth round. (Link)
Lawrence, Evans & Co. (LECO) is in Indianapolis on September 9–10, 2026 for ACG Great Lakes Capital Connection. Managing Partner Neil Johnson and Director Dave Opalek will be on-site throughout the conference and are available to meet with owners, operators, investors, and advisors.
LECO provides investment banking, financing, and consulting to small and middle-market healthcare providers and services companies, as well as logistics, technology, and business-services businesses. Typical clients are up to $250 million in revenue. The firm is known for practical solutions on complex M&A, growth capital, refinancings, and special situations.
What we have been working on
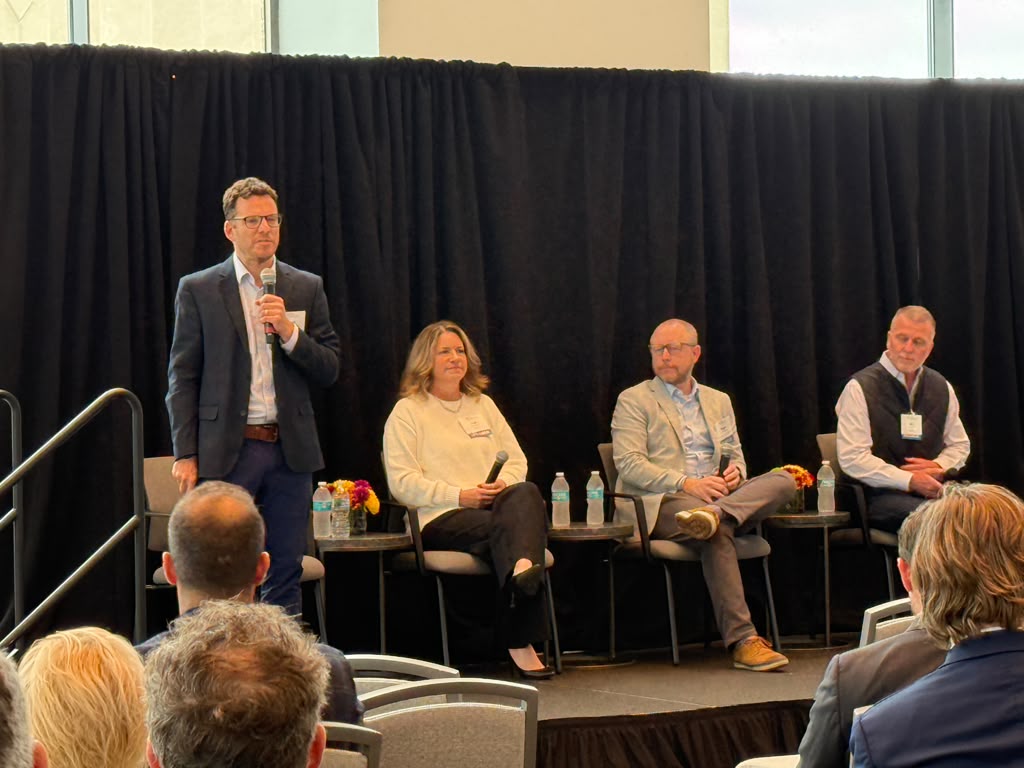
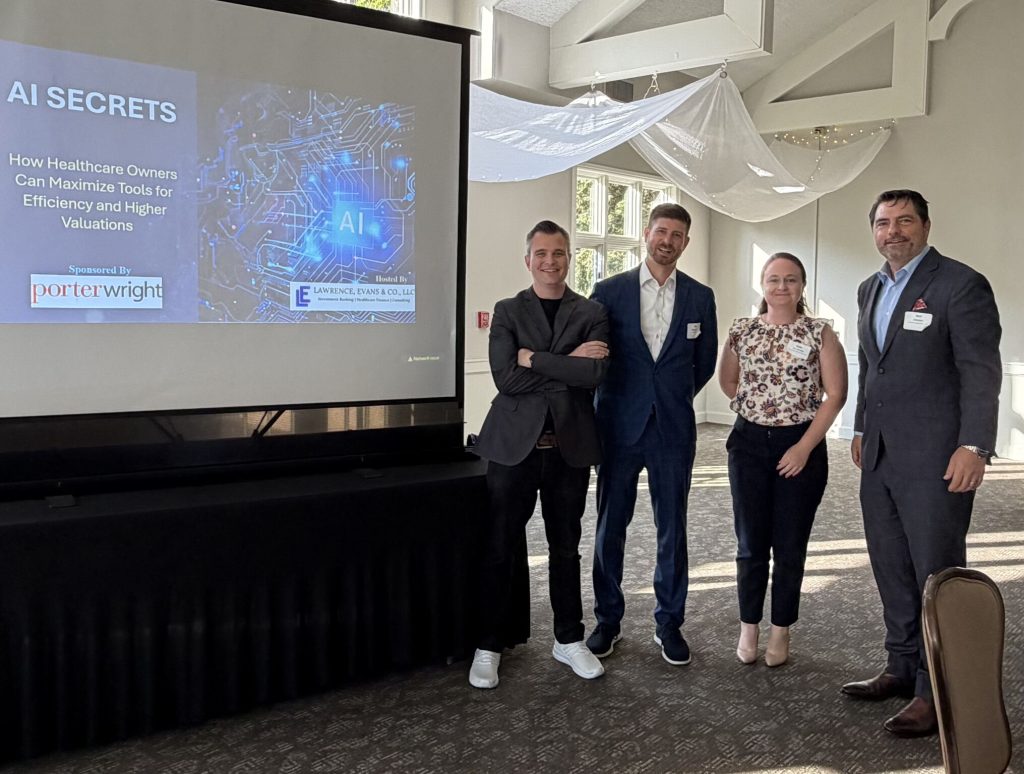
In August 2026, we hosted AI Secrets: How Healthcare Owners Can Maximize Efficiency & Valuations in partnership with Porter Wright Morris & Arthur LLP as the sponsor. The discussion focused on how owners are using AI to improve operations, protect margin, and build a more saleable business ahead of a raise or exit. Neil Johnson moderated a panel with Kathleen Van Schaik of Porter Wright, Tim Raderstorf of Steadywell, and BJ Yurkovich of Elevate CFO.
We also recently closed a $30 million refinance and growth-capital facility for a healthcare revenue cycle management platform. LECO led the process while the company completed acquisitions across multiple countries, structuring a non-dilutive refinance and acquisition line of credit around that expansion.
Earlier this year, Lawrence, Evans & Co. was presenting sponsor of the 6th Annual Healthcare Capital Markets & Innovation Summit (HCMIS) in Columbus. The 2026 program brought together nearly 500 healthcare operators, investors, lenders, and advisors around deal activity, private credit, AI, behavioral health, and longevity as an investment theme.
Why GLCC
Great Lakes Capital Connection is one of the region’s primary middle-market meetings. We will be there to compare notes on healthcare and services deal flow, listen for companies that need a refinance or acquisition facility, and stay in front of the sponsors and operators we work with across the Midwest.
If you will be in Indianapolis on September 9–10, reach out to Neil or Dave and set a time to meet. If you aren’t able to be there, please feel free to reach out by e-mail:
Neil Johnson: njohnson@lawrenceevans.com Dave Opalek: dopalek@lawrenceevans.com
Oura Inc. has publicly filed its Form S-1 with the SEC for a Nasdaq listing under the ticker OURA, with existing investors reportedly seeking up to $3 billion at a valuation above $16 billion. The public file on 3 September replaces a 21 May confidential submission and attaches audited figures. Revenue reached $1.21 billion for the nine months to 30 June 2026, up 74% from $697.6 million; fiscal 2025 revenue was $907.9 million, up 123%. Gross margin improved to 55% from 51%. The $924.3 million net loss attributable to common stockholders is a $985.0 million deemed dividend on redeemable convertible preferred — a pre-IPO capital-structure entry, not operating deterioration. Last private mark was about $11 billion in October 2025. Hardware is still roughly 80% of revenue. (Link)
Yellow Wood Partners to Buy Nestlé’s Mainstream Vitamins and Supplements Platform for $1 Billion Nestlé is keeping the premium practitioner-channel brands — Solgar and Pure Encapsulations — and selling the mass-market Holistic Health VMS book. That is how large strategics are now splitting consumer health: retain clinician-recommended margin, exit volume. Yellow Wood has run this carve-out playbook before. GLP-1-driven changes in nutrition behavior are reshuffling category economics; add-on activity is expected. (Link)
Medtronic plc has committed about $700 million to Cornerstone Robotics and taken distribution rights to Cornerstone’s Sentire surgical system in selected markets outside the United States. Sentire will sit beside Hugo (Medtronic’s robotic-assisted surgery (RAS) system) rather than replace it. The system was built in-house, finished multi-specialty trials and received CE Mark in May 2026 for general, gynecologic, thoracic and urologic minimally invasive surgery, on top of China and Singapore approvals. Cornerstone runs three global R&D hubs, six business centers and a 30,000-square-meter plant in China; the console is dual-capable. Hugo is already in more than 35 countries, with procedures expected to exceed 50,000 this fiscal year. Rights apply only where Sentire is already market-approved. (Link)
American Healthcare REIT Spends $696 Million on Eight Class A Senior Housing Communities, Launching a New LCB Operating Relationship The eight communities total 867 units across Massachusetts, Connecticut, New Jersey, Pennsylvania, Delaware and Georgia. They were carved from a ten-community sale; AHR walked the other two to a second buyer at its allocated basis — a structure owners should note when a single buyer will not take the whole book. The same week AHR closed six Kensington Senior Living communities for about $572 million, part of an eight-community, 745-unit portfolio priced near $873 million and described as well below replacement cost. Year-to-date investments now exceed $2 billion. (Link)
LTC Properties Pays $200 Million for Four Minnesota SHOP Communities at a 7% Year-One Cap Rate The four assets are 453 independent living, assisted living and memory-care units with an average age of nine years. Unlevered IRR is guided to the low- to mid-teens. About $167 million of the check came from selling 13 Texas skilled-nursing centers — a rotation out of triple-net SNF into operator-aligned seniors housing, now 38% of annualized NOI. Operator is Lifespark. Published cap-rate and IRR targets are uncommon and give private owners a reference bid. (Link)
Medtronic plc (NYSE: MDT) has agreed to invest up to $80 million in Israel’s Pi-Cardia Ltd., securing global distribution rights to the ShortCut device and an option to acquire the company for up to $210 million plus earn-outs. The check is staged into Rehovot; exclusive ShortCut distribution starts in 2027; the option is milestone-based. ShortCut is the first FDA-cleared leaflet-modification tool for valve-in-valve TAVR patients at risk of coronary obstruction, with successful leaflet splitting in every pivotal-trial patient. Structural Heart GM Jorie Soskin framed it as preparing for complex-anatomy TAVR demand rather than buying the company today. (Link)
Cresco Labs Inc. (CSE: CL; OTCQX: CRLBF) has closed the purchase of PharmaCann Penn, LLC for $50 million in cash and a seller note, adding nine operating medical-marijuana dispensaries in Pennsylvania The deal is cash-free and debt-free against a normalized working-capital target and is described as immediately accretive to revenue, margin and cash flow. Pennsylvania is the second-largest U.S. medical cannabis market, with more than $1.1 billion of sales last year. The stores deepen an existing Mid-Atlantic retail bench rather than opening a new state. No earn-out was disclosed. (Link)
Fortrea Holdings Inc. (NASD: FTRE) will buy Worldwide Clinical Trials’ Early Phase Services unit for about $45 million in cash. The package is a 200-bed GCP clinical pharmacology unit in San Antonio, a 60,000-square-foot GLP bioanalytical lab in Austin and a biospecimen store in Pflugerville. Fortrea picks up captive large- and small-molecule bioanalysis and more first-in-human beds. Worldwide keeps late-stage oncology, neuroscience, internal medicine and rare disease and will still place Phase I work through a services alliance. Close is subject to licenses and those agreements. Barclays and Mintz advised Fortrea; BroadOak and Greenberg Traurig advised Worldwide. (Link)
Discovery’s Vitality Acquires Icario in a Reported R958 Million Deal, Building a Payer Platform Covering 30% of U.S. Health Plans The combined stack reaches 19 million members, including eight of the ten largest U.S. plans. The parties themselves did not disclose value; the R958 million figure is from South African press. Member engagement is now a Stars-and-risk-adjustment revenue lever rather than a wellness line item. The buyer is a non-U.S. strategic writing a check for scaled U.S. payer distribution — a class domestic sellers should not overlook. (Link)
HCA Healthcare, Inc. (NYSE: HCA) has sold Dominion Hospital in Falls Church, Virginia to New York-based senior care operator Hill Valley Healthcare for $25 million. The buyer, founded in 2018, runs more than 40 facilities across six states. This is its first behavioural-health asset and part of a push into Virginia. Dominion treats children, adolescents and adults, including eating-disorder and trauma programmes. HCA keeps 430 inpatient behavioural beds and 19 outpatient programmes in the state. (Link)
PACS Group, Inc. (NYSE: PACS) has signed definitive agreements to acquire the operations of 32 Florida skilled nursing facilities leased from Omega Healthcare Investors, Inc. (NYSE: OHI). Florida is the company’s 21st state. The package adds 4,049 licensed beds concentrated in the Tampa, St. Petersburg and Orlando corridor, with close expected in the fourth quarter. Chairman and CEO Jason Murray framed the state as demographically driven growth; shares rose 3.3% premarket. (Link)
H.I.G. Capital has completed the acquisition of Outcomes One, the Orlando-based clinical network services and pharmacy technology provider led by Chief Executive Jude Dieterman. The Miami firm, with $75 billion under management, bought through an affiliate; terms were undisclosed. The asset pairs network reach with recurring software: a clinical network touching roughly 85% of U.S. pharmacies, more than 10 million interventions in 2025 across 130 million covered lives, and platforms including Rx30, Computer-Rx and Outcomes Premium. Managing Director Arjun Mohan framed the thesis as elevating the pharmacy’s role in care delivery. Customers span national chains, health systems, specialty and long-term care, and independents. (Link)
CVC, through its Strategic Opportunities III platform, has agreed to invest in Unitex Textile Services LLC alongside the Potack family, taking the first outside equity in the healthcare linen group’s 100-year history. Founded in 1922 and based in Elmsford, New York, Unitex is the leading outsourced healthcare textile manager in the Northeast, serving more than 5,000 hospitals, outpatient sites and nursing homes through an automated processing network. Chairman Michael, CEO Robert and President David Potack keep a significant stake and continue to run the company. Proceeds fund operations, commercial work, digital capability, greenfield sites and bolt-ons. The underwriting is scale, route density and long-tenured accounts. (Link)
Labcorp (NYSE: LH) has acquired MLM Medical Labs, expanding its central-laboratory and biomarker network across the United States, Germany and South Africa. Labcorp says that makes it the only independent central lab with a wholly owned network on four continents. MLM operates Africa’s first fully CAP-accredited central laboratory and adds biomarker and specialty testing for multinational trials. Labcorp employs about 71,000 people, supported more than 85% of FDA new-drug approvals in 2025 and ran more than 750 million tests. No price was disclosed. (Link)
Bain Capital-backed LeanTaaS has acquired Aidin, the care transition platform founded and led by Russell Graney, to extend iQueue for Inpatient Flow through discharge and placement. LeanTaaS is already in about 200 health systems and more than 1,200 facilities. Aidin serves 200-plus hospitals across roughly 20 systems and coordinates more than two million referrals a year through 21,000-plus post-acute providers. Published results: 0.86 days off average length of stay, placement time halved, and about $1.7 million of annual savings per hospital. Bain partner Paul Moskowitz framed the return as capturing both the avoided day and the freed bed. Terms undisclosed. (Link)
Stryker (NYSE: SYK) has signed a definitive agreement to acquire privately held ZuriMED, developer of the commercialized FiberLocker System for rotator-cuff augmentation. ZuriMED is a Zurich company out of ETH Zurich, the University of Zurich and Balgrist. FiberLocker is an FDA-cleared (510(k), late 2024) single-use system: a non-degradable polyester SpeedPatch PET felt plus a dedicated instrument that mechanically felts the patch into repaired cuff tissue. Published retear rates after cuff repair run from 24% to 94%; the device is indicated to reinforce suture or anchor repair where the soft tissue is weak. The parties will operate separately until close. (Link)
Quva has acquired Central Admixture Pharmacy Services’ 503B product portfolio after CAPS, a B. Braun unit, exited 503B sterile compounding. Named SKUs include cardioplegia, total parenteral nutrition and heparin. Quva runs more than 200,000 square feet of FDA-registered 503B plants in New Jersey and Texas and 100,000 square feet of forward distribution in Texas and Arizona, and already serves more than 3,500 U.S. hospitals. Selected products start later in 2026, with the rest over the following six months. Local CAPS 503B staff are being offered roles. (Link)
VION Biosciences, based in Shaker Heights, Ohio, has closed its acquisition of Prolytix. The add-on brings regulated large-molecule bioanalytical and CMC work — PK, ADA and immunogenicity, biomarkers, method validation, release and stability — plus research reagents, plasma and coagulation proteins, IVD inputs and custom collection devices. Those lines sit next to CTL immune monitoring and Ansh Labs on a Brooke PE / LongWater / Twin Bridge platform. CEO Mark Thornton framed the gap as documentation-heavy services and workflow-critical reagents. (Link)
Serent Capital-backed Aria Care Partners has acquired Precision Mobile Care, the Utah mobile dental provider led by Principal John Flanders. The Overland Park platform already delivers dental, vision, audiology and podiatry plus insurance into skilled nursing facilities and has converted a ten-year insurance relationship into ownership. Precision serves thousands of residents in more than half of Utah’s SNFs with on-site preventive and restorative dental care. This is Aria’s third acquisition of 2026, after the February Sanford dental and vision platform in Georgia and Alabama. Aria partners with more than 3,500 facilities nationally; client-facing teams and schedules stay. (Link)
Incline Equity Partners-backed West Physics Consulting, LLC has acquired Radiographic Testing Services, Inc., the Albany, New York medical physics provider. West Physics, Atlanta-based and sponsor-backed since June, is on its ninth disclosed add-on. RTS, founded in 2011, covers nuclear medicine, diagnostic radiology, radiation oncology and Certified Radiation Equipment Safety Officer work across central New York. An Albany field office lets the platform meet New York requirements centrally and reach Boston and Philadelphia. CEO Dr. Geoffrey West cited local relationships and state regulatory familiarity. (Link)
Venture Deals and Other
Noteus Partners has led a $90 million equity round in Scan.com with participation from Aviva (LSE: AV.), Concord Health Partners, YZR Capital and Oxford Capital, alongside $130 million of debt facilities from VerisFi Capital and Atempo Growth. vCombined capital is $220 million after revenue doubled to a $165 million annualised run-rate. The debt is earmarked for M&A and working capital in a U.S. imaging market where 85% of scans are still booked by fax or phone. Noteus GP Nathalie Bruls cited patient experience, provider connectivity and proprietary data; Concord’s James Olsen tied it to access and cost. More than 900,000 patients have used the network globally. (Link)
Morgan Health has led a Series E of more than $125 million in Thyme Care at a valuation above $2 billion, joined by Humana Inc. (NYSE: HUM), CVS Health Ventures — the corporate arm of CVS Health Corporation (NYSE: CVS) — AlleyCorp, HealthQuest Capital, Foresite Capital, Concord Health Partners, Frist Cressey Ventures, Town Hall Ventures and a16z Bio + Health. The syndicate pairs two national payers with community-oncology, health-system and employer-benefit capital. Reach is 10.5 million people across all 50 states and more than $7 billion of oncology spend, with validated 5–10% reductions in total cost of care. The company reports profitability and positive free cash flow. Proceeds also capitalise Thyme Companies, a new parent building independent oncology businesses aimed at biosimilar adoption and trial accrual. Morgan Health CEO Dan Mendelson cited continued conviction in payer-side value delivery. (Link)
Ultrahuman has raised $70 million — $65 million of equity and $5 million of debt — at a reported $365 million valuation, with Qualcomm Ventures, Labcorp, Alpha Wave, Blume Ventures, Nexus Venture Partners and Alteria Capital. The Bengaluru company says it has sold about 800,000 rings and is running at a $140 million revenue run-rate, targeting $200 million by January 2027. It currently uses Nordic Semiconductor silicon and is adding Qualcomm chips so more algorithms run on the ring rather than the phone or cloud. Part of the money funds a deeper link between ring physiology and Labcorp blood-testing data, plus expansion in India and the UAE. (Link)
BVF Partners, L.P. has led an oversubscribed $60 million Series B in Superluminal Medicines with new investors Deep Track Capital and Perceptive Advisors joining existing backers RA Capital Management, Insight Partners, NVIDIA Corporation (NASD: NVDA), Catalio Capital Management, Eli Lilly and Company (NYSE: LLY), Cooley and Gaingels. The round funds the move from discovery platform to clinic. NVIDIA is the compute check; Lilly is both investor and GPCR collaboration partner. Proceeds take a selective, biased MC4R agonist into Phase 1 by year-end 2026 for rare genetic and hypothalamic obesity. BVF’s Harsha Paladugu cited differentiated small molecules against historically intractable GPCRs; RA Capital’s Nandita Shangari pointed to syndicate calibre as validation of platform translation. (Link)
Elucid has closed an oversubscribed $55 million Series D with a new unnamed publicly traded medtech strategic investor joining IAG Capital Partners and Elevage Medical Technologies, the platform created by Patient Square Capital. The company raised after FDA clearance and reimbursement, not before. Total capital is about $185 million since 2009; valuation undisclosed. The new backer is Elucid’s fourth publicly traded strategic — an unusual concentration for software-only cardiovascular diagnostics. Plaque-IQ was cleared in October 2024 and has been reimbursable under CPT 75577 at a national average of about $1,012 per scan since January 2026. BioIntegrated FFR-CT remains in 510(k). Proceeds fund commercial expansion and clinical studies. (Link)
Hi Rasmus has taken a $50 million minority growth-equity investment from Updata Partners. The Nashville ABA software company was founder-controlled and previously bootstrapped. It now serves about 1,000 organizations and 19.6 million client session hours a year and ranked No. 7 on the 2026 Inc. Regionals Southeast list on 1,069% two-year growth. Braden Snyder of Updata joins the board. No change of control; management says it does not plan another raise. (Link)
EIT Pharma has closed an oversubscribed $35 million Series A led by Propel Bio Partners. EIT is taking lonafarnib, an investigational first-in-class oral therapy for chronic hepatitis D in patients already infected with hepatitis B, through FDA review. The company says it is the only oral candidate in late-stage CHD development and that the NDA has been accepted. Lonafarnib is designed for oral dosing and room-temperature storage. Good Ventures and Arrowtown joined. Proceeds fund continued FDA review, manufacturing and commercial readiness if approved, plus the rest of the infectious-disease pipeline. Safety and efficacy are not established. (Link)
Labcorp Venture Fund, the strategic arm of Labcorp Holdings Inc. (NYSE: LH), has led a $32 million Series B in N-Power Medicine with continued participation from the Merck Global Health Innovation Fund of Merck & Co., Inc. (NYSE: MRK), Innovatus Capital Partners and a leading US biotech investor. The Labcorp check is the second industry-leader investment in the Redwood City company after Merck GHI. The product is ProECA, which builds prospective, trial-grade external control arms from routine community cancer care and is meant to cut randomisation, sample size and timelines. The initial NSCLC programme runs across more than 40 community oncology sites and is already used by sponsors for early-phase and Phase 4 work. Colorectal and prostate platforms follow later this year. Proceeds scale the network and pharma partnerships. (Link)
Chicago-based PatientIQ has closed a $30 million Series C led by Hughes & Company, with Health Enterprise Partners and August Capital. The outcomes platform now covers 870-plus healthcare organizations, 17 million patients and more than 70 million collected outcomes across 20-plus specialties and 50-plus EHR integrations, including Epic, Oracle Cerner and Athenahealth. It powers registries for AAOS, AANS and STS. Proceeds fund deeper specialty and health-system penetration, real-world evidence for device and life-science customers, and a direct-to-patient marketplace. Travis Hughes joins the board. (Link)
Madrona and General Catalyst have led the close of NewDays’ seed round at $16 million, as the Seattle AI dementia care company launches in Nevada. The same pair co-led the original $7 million seed; this take-up brings the seed to $16 million total. The pitch is a staffing bottleneck: cognitive therapies work but depend on a small bench of trained clinicians. NewDays pairs monthly or twice-monthly telehealth visits with unlimited sessions with an AI companion, Sunny. Research presented at the Alzheimer’s Association International Conference in July showed patients outperforming historical decline curves by about 18 months of preserved function — on 24 patients. Nevada is the sixth state. (Link)
AI is becoming a real value-creation tool in healthcare.
Great panel and networking event this week exploring “AI Secrets: How Healthcare Owners Can Maximize Efficiency & Valuations.” We heard practical examples of how owners and providers are using AI to improve operations, drive EBITDA and build more valuable businesses ahead of a raise or exit.
AI is moving from buzzword to real value creation in healthcare.
Great discussion at our AI Secrets: How Healthcare Owners Can Maximize Tools for Efficiency & Higher Valuations event, bringing together healthcare business owners, investors and industry experts to share what’s actually working.
We explored practical ways healthcare companies are using AI to improve efficiency, reduce costs, strengthen operations and ultimately maximize value ahead of an exit.